Wikilix - Broker Reviews & Analysis

Your trusted platform for comprehensive broker reviews, analysis, and trading education. Making informed trading decisions through transparency and community insights.

Trusted by 50,000+ traders worldwide

Quick Links

  • About
  • Contact us
  • Regulators
  • Licence lookup
  • Education
  • Privacy Policy
  • Editorial Policy

Resources

  • All Brokers
  • Top Brokers
  • Scam Alerts
  • News
  • Spread Meter

Connect With Us

info@wikilix.com
support@wikilix.com
Secure & Encrypted
Global Broker Coverage

Broker categories

  • Tier 1 regulated
  • Tier 2 regulated
  • Tier 3 regulated
  • Tier 4 regulated
  • Onshore brokers
  • Offshore brokers
  • Unregulated brokers
  • Brokers by country
  • Broker rankings
© 2026 Wikilix. All Rights Reserved.

Trading involves risk. Please consider your investment objectives and risk tolerance before trading.

Wikilix
  • Home
  • Broker
  • Rankings
  • Regulators
  • Learn
  • Insights
  • Prop Firms
Contact us
Wikilix
Wikilix
Contact us

Browse

  • Home
  • Learn

Follow us

  1. Regulators
  2. /
  3. FCA
Regulator record

FCAFinancial Conduct Authority

Tier 1 onshore regulator in the United Kingdom, rated 100 of 100 on the Wikilix scale.

Check a licence on the registerOfficial website

Wikilix rating

FCA on the Wikilix scale

Updated Aug 19, 2026
Financial Conduct Authority logo

100/ 100

Six measures, each out of 100, averaged.

Tier 1Transparency highGovernment body
  • Licence value100
  • Regulatory framework100
  • Institutional strength100
  • Risk management100
  • Investment protection100
  • Client fund insurance100

Each measure is Wikilix's own assessment of the regulator, out of 100.

  1. AboutAbout
  2. Client protectionClient protection
  3. Licensing termsLicensing terms
  4. From the documentsFrom the documents
  5. Licensed brokersLicensed brokers
  6. In the newsIn the news
Filed under
  • 🥇Tier 1 regulated
  • 🏛️Onshore
  • United Kingdom
The regulator
Updated Aug 19, 2026

About FCA

The Financial Conduct Authority (FCA) regulates the conduct of around 35,500 financial firms in the UK and was established on 1 April 2013. Its authorisation is what unlocks two consumer protections: the Financial Ombudsman Service, which can order awards up to £455,000 for complaints referred on or after 1 April 2026, and the Financial Services Compensation Scheme, which pays up to £85,000 per person per firm for investment claims where the firm has failed. For retail CFD and rolling spot forex accounts, FCA rules cap leverage at between 30:1 and 2:1 and require close out at 50% of required margin. A firm without FCA permission for the activity it is selling you carries neither of those protections.

Tier 1
Brokers on the recordBrokers on the Wikilix record holding at least one licence or registration from this regulator.
271
Compensation cap (FSCS)What a client can recover from the regulator's compensation scheme if a licensed firm fails, as the regulator's own record states it.
£85,000
Retail leverage capThe highest leverage the regime allows a retail client, as recorded for this regulator.
1:30
Cost of a licenceWhat the regulator's record gives as the cost of obtaining a licence, including setup where stated.
£100,000+

The Financial Conduct Authority (FCA) is a single regulator for financial services and markets in the UK.It is an independent body, established on 1 April 2013, under the Financial Services Act 2012, and replaces the previous body for regulating financial services in the UK, the Financial Services Authority (FSA).

Unlike many bodies, the FCA is funded by fees from the firms it regulates rather than government funding.The FCA operates independently but is accountable to the UK Treasury and Parliament, both of whom can oversee its objectives and performance.

What does the FCA do and why does it matter?

The FCA regulates approximately 42,000 financial providers and supervises the prudential health of roughly 41,000 firms, of which approximately 17,000 have detailed rules in the FCA’s official handbook.

At its simplest form, the FCA regulates whether or not the UK’s financial markets operate effectively, efficiently, and fairly. Some of the key responsibilities of the FCA are to;

• Increase transparency so consumers understand what they are signing up for.

• Protect people from immoral or dishonest practices

• Encourage innovation to help businesses grow and compete

• Maintain fair competition so that one company does not dominate all of the market.

Financial services underpin almost everybody’s life, for savings accounts, pensions, mortgages, insurance, loans, etc. Businesses depend on financial services too for investment, growth, and hiring.Additionally, the sector is an essential foundation of the UK economy, employing over a million people and adding billions of pounds every year.

FCA Objectives

The FCA’s primary objective is that financial markets function well for everyone. The FCA’s operational objectives are:

1.To protect consumers by ensuring they are treated fairly and can access the products and services they need.

2.To protect and enhance the integrity of the UK financial system and the public’s trust in it.

3.To promote competition in the interests of consumers, facilitating innovation and better consumer outcomes.

Since 2023, the FCA has also added operational objective aimed at improving the UK’s global competitiveness and economy in a sustainable way and in alignment with international regulatory standards.

FCA: How it Works – Where it Works

The FCA is headquartered in London with offices in Leeds, Edinburgh, Belfast, and Cardiff. The FCA carries out its duties in the UK and closely works with the Prudential Regulatory Authority (PRA), which supervises approximately 1,500 banks, insurers, and investment firms, as well as other regulators and government departments.

To deliver its operational objectives, the FCA employs a range of tools to ensure and enable its mission to ensure that financial markets work well for everyone, such as:

• creating rules and guidance to ensure firms understand their obligations;

• undertaking market studies that identify harmful practices, then invite firms to address them;

• authorising and registering firms to ensure only suitable businesses operate in the market;

• supervising firms to ensure they meet the FCA’s standards once they are open for business;

• imposing sanctions in the form of monetary penalties, as well as criminal punishment for severe infringements.

The FCA uses a data-driven, risk-based approach and focuses on firms and areas that will result in greater outcomes for consumers and the broader financial system. This is also designed to enable the FCA to react quickly in the event of threats, risks, and less-than-optimal market behaviour.

Protecting Consumers and Markets

The FCA goes beyond writing rules to do the following:

• Protect consumers from harm;

• Combat illicit financial crime and avoid fraudulent practices;

• Protect the UK market integrity by ensuring it remains open and fair.

The FCA also collaborates with other global regulators and organisations to ensure that UK markets can remain competitive and aligned with international best practice.

In fact, the FCA estimates that every £1 of expenditure converts to a benefit to society of roughly £14.This emphasises the FCA’s position as a regulator to maintain a stable, fair and efficient financial system.
 

On the record

Established
2013
Country
United Kingdom
Oversight
Government body
Scope
Regulates forex and CFD brokers
Membership
IOSCO and FATF member
Transparency
High
Public register
Open the register
Website
fca.org.uk
Phone
44 2070661000
Hotline
020 7066 9870
Email
consumer.queries@fca.org.uk
Online contact
fca.org.uk
Related site
financial-ombudsman.org.uk
Protection check

What a licence from FCA protects

Under FCA rules, client money at a licensed firm is covered by a compensation scheme, and a dispute the firm will not settle can go to Financial Ombudsman Service.

5 facts on record
  • Compensation schemeUp to £85000 (FSCS)
  • Client money kept separate
  • Negative balance protection
  • Complaints routeFinancial Ombudsman Service
  • Maximum leverage1:30

What is protected

Protection follows the permission, not the brand. The FCA states that if you deal with a firm that is not authorised, or that lacks permission for the activity you need, you have no access to the Financial Ombudsman Service and no Financial Services Compensation Scheme cover if the firm fails. Where cover does apply, FSCS pays up to £85,000 per eligible person per firm for investment claims about firms that failed after 1 April 2019, and up to £120,000 per eligible person for deposits with a UK-authorised bank, building society or credit union that failed after 30 November 2025. FSCS does not pay for poor investment performance, and the FCA lists high-cost short-term credit, money held with e-money institutions, authorised payment institutions and small payment institutions as outside FSCS cover. FCA Principle 10 requires a firm to arrange adequate protection for clients' assets when it is responsible for them.

How to verify a licence

Search the firm on the Financial Services Register at https://register.fca.org.uk/, or use the FCA Firm Checker at https://www.fca.org.uk/consumers/check-if-firm-fca-authorised before you buy a product. Search by firm name or firm reference number, then read three things on the result: the status, the permissions, and the contact details. The FCA states that a firm showing as 'No longer authorised' or 'Revoked' can no longer carry out any regulated financial activities. Check that the permission covers the exact service being sold to you, since being registered is not the same as being authorised. Compare the phone number, website and address on the Register with the ones the firm gave you, because clone operations copy the details of genuine authorised firms. If the firm is listed as an appointed representative, ask its principal to confirm what activities it may carry out. The Firm Checker may take, on average, 24 hours to reflect a change, and the FS Register is the place to look for an individual, a historic record, or a firm that was authorised in the past.

Open the registerOfficial website

How to complain

Complain to the firm first. FCA rules give you 6 years from the problem happening, or, if later, 3 years from when you became aware you had cause to complain. The firm must reply in writing with the outcome within 8 weeks in general, and payment service providers and e-money issuers must normally respond to certain complaints within 15 business days. If you are unhappy with the answer, take it to the Financial Ombudsman Service, which is free to use, within 6 months of the date on the final response. The Ombudsman can tell a business to pay up to £455,000 for complaints referred on or after 1 April 2026 about acts or omissions on or after 1 April 2019, and up to £205,000 where the act or omission was before 1 April 2019.

Hotline
020 7066 9870
These are the rules FCA sets for the firms it licenses, read from its own record. They say nothing about how any one broker applies them, or which of its companies would hold your account; that is checked on each broker's own page.
Licensing terms

Getting licensed by FCA

A licence from FCA costs £100,000+ to obtain on the record and covers 9 instrument types.

£100,000+
Licence types
MiFID Investment Firm – Dealing on Own Account / Matched Principal (retail & market-making CFDs)
Business models allowed
Retail Agency (STP); Market Maker (Principal); Provide Liquidity (PoP)
Cost to obtain
£100000+ (including compliance setup)
Coverage
UK - EU - global (with exceptions)
Not served
USA - North Korea - Iran - other sanctioned countries

9 instruments regulated

  • Forex
  • Bond
  • Stocks
  • Fund
  • Options
  • Derivatives
  • Commodity
  • Loan
  • Retail Investment

Restricted for retail clients

  • Binary option

Products FCA does not allow licensed firms to offer retail clients, as recorded.

From the documents
Reviewed Aug 19, 2026

What FCA's own documents say

22 facts read from 28 official documents published by FCA, each quoted and linked to its source.

22 facts

Jurisdiction and scope

The FCA regulates financial services firms in the UK and sets the standards they must meet. Authorisation covers named regulated activities including investments such as shares, funds and derivatives, bank accounts, lending, insurance, home finance, pensions, claims management, and payment and e-money services. Certain crypto activities are registration only, for anti-money laundering purposes, rather than a conduct authorisation. Buy-to-let mortgages, commercial mortgages and lending, timeshares, unregulated Buy Now Pay Later, and advice on wills and probate sit outside the regulated or supervised list. The FCA states that authorised firms can offer both regulated and unregulated products, and that its powers over the unregulated ones are more limited.

Using this regulator

Look up the firm reference number on the Financial Services Register and confirm the permission matches the service being offered, then confirm the phone number and website against the Register entry. If the entity you are dealing with is an appointed representative, ask the principal to confirm in writing what it may do and how you would be covered. For CFD, spread bet and rolling spot forex accounts, a UK-authorised firm must cap retail leverage at between 30:1 and 2:1, close out at 50% of required margin, and guarantee you cannot lose more than the funds in the account, so an offer of higher retail leverage is a sign you are not dealing with the UK-regulated entity. Keep the firm's final response letter, since the 6-month clock for the Financial Ombudsman runs from its date. You never need a claims management company: complaining to the firm, the Ombudsman and FSCS is free, while the FCA notes CMC and law firm charges of up to 36% including VAT out of any compensation.

Good to know

This dossier covers the FCA's authorisation and registration, the public register and how to check a firm, the complaint route and its deadlines, the compensation scheme and client-money protection, and the published application fees.

Key facts

KeyVerifying a licence

Check the firm on the Financial Services Register first

It takes a minute to confirm that the firm reference number a broker quotes is real, current, and attached to the activity being sold to you. A revoked or lapsed entry is the clearest signal to stop.

The FCA states that the FS Register is the official public record for all firms and individuals, and that a firm showing as 'No longer authorised' or 'Revoked' can no longer carry out any regulated financial activities.

The FS Register is the official public record for all firms and individuals.
Quoted in How to check a firm or individual is authorisedRead the source
On the FS Register, when a firm shows as 'No longer authorised' or 'Revoked' it can no longer carry out any regulated financial activities.
Quoted in How to check a firm or individual is authorisedRead the source

Where in the document: How to check a firm or individual is authorised, sections 'How to check a firm or individual' and 'No longer authorised or revoked firms'

  • public register
  • license verification
  • retail clients
KeyCompensation scheme

FSCS pays up to £85,000 per person per firm for investments

GBP 85,000

This is the ceiling on what you get back if an investment firm fails, and it is per firm, so a larger balance with a single provider sits above the cap. Losses from the market moving against you are outside the scheme entirely.

For investment claims where the firm failed after 1 April 2019, the Financial Services Compensation Scheme can pay up to £85,000 per eligible person per firm. It does not accept claims for poor investment performance.

We can pay up to £85,000 per person, per firm.
QuotedRead the source
We can't accept any claims that are for poor investment performance - unfortunately, the nature of investments means their value can go down as well as up.
QuotedRead the source
For FSCS to be able to protect you, the PRA or the FCA must have authorised the provider or adviser, as well as regulated the service and product it provided.
QuotedRead the source

Where in the document: FSCS Investments, sections 'Compensation limits' and 'Claims, what you need to know'

  • retail clients
  • compensation
  • investor protection
KeyHow to complain

Six years to complain, six months to escalate

The 6-month escalation window is the one people lose. Keep the firm's final response letter, since its date starts that clock, and the Ombudsman may not be able to help once it has run.

FCA rules give you 6 years from the problem happening, or if later 3 years from when you became aware of it, to complain to the firm. Firms must generally give the outcome in writing within 8 weeks, and the Financial Ombudsman Service must be contacted within 6 months of the date on the final response.

You normally need to complain within 6 years of the problem happening or, if later, within 3 years of you becoming aware that you had cause to complain.
Quoted in How to complainRead the source
It’s important you contact the Financial Ombudsman within 6 months of receiving a final response from the firm, or they may not be able to help.
Quoted in How to complainRead the source
You will need to make a complaint to us within 6 months from the date on your final response.
Quoted in How to complain (Financial Ombudsman Service)Read the source

Where in the document: How to complain, steps 1 to 3

  • retail clients
  • complaint deadline
  • ombudsman
KeyCompensation scheme

Ombudsman awards are capped at £455,000

GBP 455,000

This is the most a free complaint route can win you, and older conduct is capped far lower. Above the limit the Ombudsman can recommend more, but the business does not have to accept that recommendation.

The Financial Ombudsman Service can tell a business to pay up to £455,000 for complaints referred on or after 1 April 2026 about acts or omissions on or after 1 April 2019, and up to £205,000 where the act or omission happened before 1 April 2019.

£455,000 for complaints referred to us on or after 1 April 2026 about acts or omissions that occurred on or after 1 April 2019.
Quoted in Understanding compensation for financial lossRead the source
£205,000 for complaints referred to us on or after 1 April 2026 about acts or omissions that occurred before 1 April 2019.
Quoted in Understanding compensation for financial lossRead the source
There is a limit to how much we can tell a business to pay when we uphold complaints. We can recommend they pay you more if we think it’s fair, but the business doesn’t have to accept that recommendation.
Quoted in Understanding compensation for financial lossRead the source

Where in the document: Understanding compensation for financial loss, section 'The limits that apply'

  • retail clients
  • compensation
  • ombudsman
KeyLeverage rules

Retail CFD leverage is capped between 30:1 and 2:1

1:3

If a broker offers you retail leverage above 30:1 on a major currency pair, you are being onboarded to something other than the UK-authorised entity. The same rules give you margin close-out and negative balance protection.

FCA rules require firms selling CFDs and CFD-like options to retail clients to limit leverage to between 30:1 and 2:1, close out a position when funds fall to 50% of the margin needed, and guarantee that a client cannot lose more than the total funds in the CFD account. References to CFDs include financial spread bets and rolling spot forex.

Limit leverage to between 30:1 and 2:1.
Quoted in FCA confirms permanent restrictions on the sale of CFDs and CFD-like options to retail consumersRead the source
Close out a customer’s position when their funds fall to 50% of the margin needed to maintain their open positions on their CFD account.
Quoted in FCA confirms permanent restrictions on the sale of CFDs and CFD-like options to retail consumersRead the source
References to CFDs include financial spread bets and rolling spot forex products.
Quoted in FCA confirms permanent restrictions on the sale of CFDs and CFD-like options to retail consumersRead the source

Where in the document: Press release of 1 July 2019, list of requirements for firms

  • retail clients
  • leverage cap
  • cfd
  • forex
KeyScope of authorisation

Crypto firms are registered for anti-money laundering purposes

A crypto platform on the FCA's list is supervised for money laundering controls, which is a narrower thing than conduct authorisation. Treat an anti-money laundering registration as a fact about financial crime checks, not as evidence that the trading service itself is FCA regulated.

The FCA lists certain crypto activities, including crypto exchanges, crypto ATMs and custodian wallet providers, as activities where firms are registered with the FCA for anti-money laundering purposes rather than authorised for conduct.

Certain crypto activities, for example, crypto exchanges, crypto ATMs and custodian wallet providers (those crypto firms are registered with us for anti-money laundering purposes).
Quoted in How to check a firm or individual is authorisedRead the source

Where in the document: How to check a firm or individual is authorised, section 'Products and services we supervise'

  • scope of authorisation
  • cryptoassets

More facts, by topic

The Firm Checker can take 24 hours to reflect a changeThe FCA runs two lookups: the Firm Checker for buying decisions and the fuller FS Register for individuals, historic records, fines and client money permissions. The FCA states the Firm Checker cannot confirm that FSCS or Ombudsman protection will apply, so use it as the first check rather than the last one.1 fact
UsefulPublic register

Firm Checker updates can take 24 hours to appear

A clean Firm Checker result is a starting point, not a guarantee of cover. For an individual, a historic record, historic fines or a firm's ability to handle client money, the fuller FS Register entry is the place to look.

The FCA states that the Firm Checker may, on average, take 24 hours to update information, and that the tool cannot confirm whether FSCS or Financial Ombudsman Service protection will definitely apply.

This tool can't confirm whether Financial Services Compensation Scheme (FSCS) or Financial Ombudsman Service protection will definitely apply if something goes wrong.
Quoted in FCA Firm CheckerRead the source
We try to make sure that this tool is always up to date. But it may, on average, take 24 hours to update information.
Quoted in FCA Firm CheckerRead the source

Where in the document: FCA Firm Checker, section 'Information you won't find on this tool'

  • public register
  • license verification
Both UK protections switch on only where the firm holds the right permissionDeal with a firm that is not authorised, or that lacks permission for the activity, and the FCA states you have neither Financial Ombudsman Service access nor FSCS cover. Even inside the perimeter there are gaps: money held with e-money institutions, authorised payment institutions and small payment institutions is outside FSCS cover.2 facts
KeyWhat is protected

Ombudsman and FSCS access depends on the permission

Both UK protections are switched on by the firm's permission, not by its marketing. Matching the service you are buying to a permission on the Register is the step that keeps both routes open to you.

The FCA states that if you deal with a firm that is not authorised, or that does not have permission for the activities you need, you have no access to the Financial Ombudsman Service and no FSCS protection if the firm goes out of business.

If you deal with a firm that isn't authorised or doesn't have permission for the activities you need, you won’t have access to the Financial Ombudsman Service if you want to complain.
Quoted in How to check a firm or individual is authorisedRead the source
You also won’t be protected by the Financial Services Compensation Scheme (FSCS) if the firm goes out of business. This means it's unlikely you'd get your money back.
Quoted in How to check a firm or individual is authorisedRead the source

Where in the document: How to check a firm or individual is authorised, section 'Using authorised firms'

  • retail clients
  • scope of authorisation
  • compensation
UsefulWhat is protected

Some firms and activities sit outside FSCS cover

Money parked with an e-money or payment institution is not deposit protected in the way a bank balance is, even though the firm is FCA authorised. It matters when a platform holds your funds through a payments entity.

The FCA names high-cost short-term credit, money held with e-money institutions, authorised payment institutions and small payment institutions as examples of firms and activities that are not covered by the FSCS.

Some firms and activities aren't covered by the FSCS (for example, high-cost short-term credit, money held with e-money institutions, authorised payment institutions and small payment institutions).
Quoted in How to claim compensation if a firm failsRead the source
If the firm was never authorised, you won’t have access to the Financial Services Compensation Scheme (FSCS) and you may not be protected if it goes out of business.
Quoted in How to claim compensation if a firm failsRead the source

Where in the document: How to claim compensation if a firm fails, step 4 'Contact the FSCS'

  • compensation
  • client money
  • e money
Principle 10 makes client asset protection an enforceable ruleEvery FCA authorised firm must arrange adequate protection for clients' assets when it is responsible for them, and must maintain adequate financial resources. These Principles for Businesses sit behind the client money wording in a broker's terms, so ask which entity holds your funds and under which permission.1 fact
UsefulClient-money rules

Principle 10 requires adequate protection of client assets

These Principles are enforceable rules that every authorised firm is held to, which is what stands behind the client money arrangements a broker describes in its terms. Ask which entity holds your money and under which permission.

FCA Principle for Businesses 10 states that a firm must arrange adequate protection for clients' assets when it is responsible for them, and Principle 4 requires a firm to maintain adequate financial resources.

A firm must arrange adequate protection for clients' assets when it is responsible for them.
Clause Principle 10 in Principles of good regulationRead the source
A firm must maintain adequate financial resources.
Clause Principle 4 in Principles of good regulationRead the source

Where in the document: Principles of good regulation, section 'Principles for businesses'

  • client money
  • segregation
  • handbook
FSCS pays up to £85,000 for investments and the Ombudsman can award up to £455,000£85,000 per eligible person per firm is the FSCS ceiling for investment claims where the firm failed after 1 April 2019, and £120,000 per person covers deposits at a failed UK-authorised bank. The Financial Ombudsman Service can order up to £455,000 for complaints referred on or after 1 April 2026 about conduct on or after 1 April 2019. Losses from investments simply performing badly are outside the FSCS entirely.1 fact
UsefulCompensation scheme

Deposits are protected up to £120,000 per person

GBP 120,000

If a trading account's cash is held at a UK-authorised bank in your name, this is the figure that applies to it. The limit is per institution, so two brands sharing one banking licence share one limit.

FSCS deposit protection covers up to £120,000 per eligible person, per bank, building society or credit union that failed after 30 November 2025, with certain qualifying temporary high balances protected up to £1.4 million for six months.

up to £120,000 per eligible person, per bank, building society or credit union.
Quoted in What we coverRead the source
On 1 December 2025 the FSCS deposit protection limit rose to £120,000.
Quoted in Financial Services Compensation SchemeRead the source

Where in the document: FSCS What we cover, section 'Banks, building societies and credit unions'

  • compensation
  • deposit protection
Six years to complain to the firm, six months to reach the OmbudsmanYou normally have 6 years from the problem, or 3 years from becoming aware of it, to complain to the firm, which must give its outcome in writing within 8 weeks in general and within 15 business days for certain payment and e-money complaints. From the date on that final response you have 6 months to take it to the Financial Ombudsman Service, which is free to use.2 facts
UsefulHow to complain

Payment and e-money complaints run on shorter clocks

15 working days

If your funding or withdrawal route goes through a payment or e-money firm, that firm answers on a faster timetable than the general 8-week rule, which brings forward the date you can go to the Ombudsman.

Payment service providers and e-money issuers must normally respond to certain complaints within 15 business days, and a final response must follow within 35 business days from the day the complaint was first made.

Payment service providers and e-money issuers must normally respond to certain complaints within 15 business days. If they can't provide a final response, they must explain the reasons for the delay.
Quoted in How to complainRead the source
In general, firms must get back to you in writing to let you know the outcome of your complaint within 8 weeks.
Quoted in How to complainRead the source

Where in the document: How to complain, step 2 'You get a response'

  • e money
  • complaint deadline
  • payments
UsefulHow to complain

Claims companies can charge up to 36% of compensation

36%

Every step of the UK route, the firm, the Ombudsman and the FSCS, is free to use. Paying a third party a share of the award buys convenience, not access.

The FCA states that signing up with a claims management company or law firm can cost up to 36% in fees, including VAT, out of any compensation received, and that complaining yourself is free.

If you sign up to a CMC or law firm, you may end up paying for a service you don't need, including up to 36% in fees, including VAT, out of any compensation you receive.
Quoted in Car finance claimsRead the source
It’s free and simple to make a complaint yourself.
Quoted in How to complainRead the source

Where in the document: Car finance claims, section 'Using claims management companies (CMC)'

  • claims management
  • complaint route
  • fees
Authorised, registered and appointed representative each mean something differentAuthorisation means the FCA has given permission for named activities. Registration means the firm meets requirements without needing that permission, which is how certain crypto firms sit on the list for anti-money laundering purposes. An appointed representative acts under a principal's permission, and going beyond what the principal allowed can leave you outside Ombudsman and FSCS cover.2 facts
KeyScope of authorisation

Authorised and registered mean two different things

A firm that says it is 'FCA registered' is not making the same claim as a firm that is FCA authorised. Read the status on the Register entry and check which activities the permission actually names.

The FCA states that being authorised means a firm has its permission to provide certain products and services, while being registered means the firm meets certain requirements but does not need FCA permission to provide products and services.

Being authorised means that firms must meet certain standards and have our permission to provide certain products and services.
Quoted in How to check a firm or individual is authorisedRead the source
Being registered means that firms must meet certain requirements, but they don’t need to have our permission to provide products and services.
Quoted in How to check a firm or individual is authorisedRead the source

Where in the document: How to check a firm or individual is authorised, opening section

  • license verification
  • scope of authorisation
UsefulScope of authorisation

Appointed representatives act under another firm's permission

If the name on your contract is an appointed representative, your protection runs through its principal. Ask the principal to confirm what the representative may offer and how you would be covered.

An appointed representative carries out activities on behalf of a principal firm, which agrees what the representative may do and is responsible for that business. The FCA states that if a representative has gone beyond the activities the principal allowed, you may not be protected by the Financial Ombudsman or the FSCS.

ARs can have more than one principal. The principal agrees what activities the AR can do and is responsible for that business.
Quoted in How to check a firm or individual is authorisedRead the source
If an AR has gone beyond the activities the principal has allowed, you may not be protected by the Financial Ombudsman or the FSCS if something goes wrong.
Quoted in How to check a firm or individual is authorisedRead the source

Where in the document: How to check a firm or individual is authorised, section 'Appointed representatives'

  • scope of authorisation
  • appointed representatives
A complete application is usually assessed within six months6 months is the usual assessment time for a complete FSMA application, 3 months for payments and e-money firms, and up to 12 months where the application is incomplete. A firm must not carry on the regulated activity while it waits, and the FCA treats doing so without authorisation as a criminal offence.1 fact
UsefulLicensing requirements

Complete applications are usually assessed within six months

A firm that says its FCA licence is 'pending' cannot lawfully take your business for the regulated activity yet. The FCA treats carrying on regulated activities without authorisation as a criminal offence.

The FCA usually assesses a complete application within 6 months for a FSMA firm and 3 months for a payments or e-money firm, and states that an incomplete application could take up to 12 months. A firm must not perform regulated activities while its application is under review unless an exemption or temporary permission applies.

If your application isn't complete, it could take up to 12 months.
Quoted in How to apply for authorisation or registrationRead the source
Your firm must not start performing regulated activities while your authorisation application is under review unless an exemption or temporary permission applies. Carrying on regulated activities without being authorised is a criminal offence and we can take enforcement action.
Quoted in How to apply for authorisation or registrationRead the source

Where in the document: How to apply for authorisation or registration, sections 'The application process' and 'How to check if you need FCA authorisation'

  • licensing requirements
  • authorisation
An authorised firm can still sell products the FCA does not regulateThe FCA states its powers over unregulated products and services are more limited, and it lists buy-to-let mortgages, commercial lending, timeshares and unregulated Buy Now Pay Later among the things it does not regulate or supervise. Match the specific service you are buying to a permission on the Register, because that is what decides your protections.1 fact
UsefulJurisdiction and limits

Authorised firms may also sell unregulated products

An FCA firm reference number attaches to the firm, not to every product on its shelf. Ask which specific service you are buying is a regulated activity, because that answer decides whether the Ombudsman and FSCS routes exist for it.

The FCA states that firms it authorises can offer both regulated and unregulated products and services, and that its powers over the unregulated ones are more limited. Buy-to-let mortgages, commercial lending, timeshares and unregulated Buy Now Pay Later are on its list of products it does not regulate or supervise.

Firms we authorise can offer both regulated and unregulated products and services. But we have more limited powers over unregulated products and services.
Quoted in How to check a firm or individual is authorisedRead the source

Where in the document: How to check a firm or individual is authorised, section 'Products and services we do and don't regulate'

  • scope of authorisation
  • jurisdiction limits
An FCA application costs between £280 and £225,170, plus an annual fee£280 is the category 1 application fee and £225,170 the category 10 fee, across 10 pricing categories set by the permissions applied for. The application fee is a one-off and non-refundable payment, and every authorised firm then pays a periodic fee each year.1 fact
UsefulCost to get licensed

Application fees run from £280 to £225,170

GBP 225,170

It shows what a UK licence costs a firm at entry, which is a useful measure of how much a broker has committed to the regime. The annual periodic fee is separate and continues for as long as the permission is held.

The FCA sets 10 pricing categories for authorisation applications, with fees from £280 for category 1 up to £225,170 for category 10. The application fee is a one-off payment and is non-refundable, and an authorised firm then pays a periodic fee every year.

Application fees range from £280 for category 1, up to £225,170 for category 10.
Quoted in Authorisation and registration application feesRead the source
The authorisation application fee is a one-off payment, but once authorised you will pay us a periodic fee each year.
Quoted in Authorisation and registration application feesRead the source
the fee is non-refundable
Quoted in Authorisation and registration application feesRead the source

Where in the document: Authorisation and registration application fees, sections 'Pricing categories', 'How to pay' and 'The FCA annual fee'

  • licence fee
  • cost to obtain
The FCA is a member of IOSCO, the FSB and the IAISMembership of the International Organisation of Securities Commissions puts the FCA inside the main global standard-setting group for securities regulators. It has also signed information-sharing agreements with overseas regulators, which is the channel used when a case crosses borders.1 fact
ContextMembership and standing

The FCA is a member of IOSCO and the FSB

IOSCO membership is the marker most often used to separate established securities regulators from newer offshore registries. It also means cross-border information sharing with other members is an existing channel.

The FCA states that it is a member of the Financial Stability Board, the International Organisation of Securities Commissions (IOSCO) and the International Association of Insurance Supervisors, and that it has signed agreements with overseas regulators to cooperate and exchange information.

We are a member of : the Financial Stability Board (FSB) the International Organisation of Securities Commissions (IOSCO) the International Association of Insurance Supervisors (IAIS)
Quoted in International standards and regulationsRead the source
We have signed a variety of agreements with overseas regulators, which help us cooperate and exchange information.
Quoted in International standards and regulationsRead the source

Where in the document: International standards and regulations, section 'Global'

  • iosco
  • international standards
The FCA Handbook holds the rules every authorised firm must followAll regulated firms must comply with the rules in the FCA Handbook, and dual-regulated firms must also follow the PRA Rulebook. When a broker cites a rule reference, the Handbook site is where the current wording and earlier versions can be compared.1 fact
ContextKey definitions

The FCA Handbook is the rulebook firms must follow

When a broker cites a rule reference such as COBS or CASS, it is pointing at the Handbook at handbook.fca.org.uk, where the current text and previous versions can be compared.

The FCA states that all regulated firms must comply with its rules as set out in the FCA Handbook, and that dual-regulated firms must also refer to the Prudential Regulation Authority Rulebook.

All regulated firms must comply with our rules as set out in the FCA Handbook.
Quoted in Handbook of rules and guidanceRead the source
Dual-regulated firms will need to consider both FCA and Prudential Regulation Authority​ (PRA) rules, so should also refer to the PRA Rulebook.
Quoted in Handbook of rules and guidanceRead the source

Where in the document: Handbook of rules and guidance, opening section

  • handbook
  • rulebook
Penalties go to the Treasury while the FCA is funded by firm feesAround 35,500 firms are regulated for conduct by the FCA, which was established on 1 April 2013 and is funded entirely by the fees it charges those firms. Financial penalties are paid to the Treasury apart from certain retained enforcement costs, so a fine against a broker is not itself a route to getting money back.2 facts
ContextOther useful facts

Fines go to the Treasury, not to consumers

A large fine against a broker does not become a payout to its clients. Money back comes through the firm, the Financial Ombudsman Service or the FSCS, which are separate routes from enforcement.

Under the Financial Services Act 2012 the FCA must pay the financial penalties it receives from firms and individuals to the Treasury, apart from amounts equal to certain of its enforcement costs, which it retains.

Under the Financial Services Act 2012, we must pay the financial penalties we receive from firms and individuals to the Treasury, except to the extent they equal certain of our enforcement costs (retained penalties).
Quoted in EnforcementRead the source

Where in the document: Enforcement, section 'Financial penalties'

  • enforcement
  • penalties
ContextOther useful facts

The FCA regulates around 35,500 firms since 2013

35,500

It sets the scale and the age of the regime a broker is pointing at, and explains why an FCA firm reference number is checkable against a single national register rather than a licence certificate.

The FCA regulates the conduct of around 35,500 firms, was established on 1 April 2013 taking over from the Financial Services Authority, and is an independent public body funded entirely by the fees it charges regulated firms.

We were established on 1 April 2013, taking over conduct and relevant prudential regulation from the Financial Services Authority (FSA).
QuotedRead the source
We regulate the conduct of around 35,500 firms.
QuotedRead the source
We're an independent public body funded entirely by the fees we charge regulated firms.
QuotedRead the source

Where in the document: About the FCA, section 'Our role'

  • about
  • funding
  • scale

28 documents examined

  • Official documentTranscript (PDF)fetched Aug 19, 2026
  • Official documentTranscript (PDF)fetched Aug 19, 2026
  • Official documentTranscript (PDF)fetched Aug 19, 2026
  • Official documentTranscript (PDF)fetched Aug 19, 2026
  • Compensation schemeFinancial Services Compensation Schemefetched Aug 19, 2026
  • Complaints procedureMake a complaintfetched Aug 19, 2026
Show 22 more documentsShow fewer
  • Complaints procedureBring a complaint to usfetched Aug 19, 2026
  • Complaints procedureLog in to Ombudsman Connectfetched Aug 19, 2026
  • Complaints procedureFor consumersfetched Aug 19, 2026
  • Complaints procedureFor businessesfetched Aug 19, 2026
  • Public registerFinancial Services Registerfetched Aug 19, 2026
  • Enforcement policyEnforcementfetched Aug 19, 2026
  • HandbookHandbook of rules and guidancefetched Aug 19, 2026
  • HandbookPrinciples of good regulationfetched Aug 19, 2026
  • HandbookPrint Pagefetched Aug 19, 2026
  • RulebookInternational standards and regulationsfetched Aug 19, 2026
  • Licensing requirementsAuthorisationfetched Aug 19, 2026
  • Complaints procedureCar finance claimsfetched Aug 19, 2026
  • Public registerFCA Firm Checkerfetched Aug 19, 2026
  • Compensation schemeHow to claim compensation if a firm failsfetched Aug 19, 2026
  • Licensing requirementsHow to check a firm or individual is authorisedfetched Aug 19, 2026
  • Complaints procedureHow to complainfetched Aug 19, 2026
  • Licensing requirementsHow to apply for authorisation or registrationLast updated 03/03/2026 · fetched Aug 19, 2026
  • Fee scheduleAuthorisation and registration application feesLast updated 13/07/2026 · fetched Aug 19, 2026
  • GuidanceFCA confirms permanent restrictions on the sale of CFDs and CFD-like options to retail consumers01/07/2019 · fetched Aug 19, 2026
  • Complaints procedureHow to complain (Financial Ombudsman Service)fetched Aug 19, 2026
  • Compensation schemeUnderstanding compensation for financial lossLast updated 1 April 2026 · fetched Aug 19, 2026
  • Compensation schemeWhat we coverfetched Aug 19, 2026
Read by Wikilix from FCA's published documents; every fact links to the page or file it came from.Last reviewed Aug 19, 2026
Licensed brokers

Brokers licensed by FCA

271 brokers on the Wikilix record hold a licence from FCA; the 10 highest-scored are below, and the finder searches them all.

271 brokers

  1. Rank 101

    Marex

    Regulated
    United Kingdom · since 2005· Marex Group
    Wikilix score 91.3
  2. Rank 202

    Market Securities

    Regulated
    United Kingdom · since 2007
    Wikilix score 89.7
  3. Rank 303

    Jefferies

    Regulated
    United States · since 1962· Jefferies Financial Group
    Wikilix score 89.0
  4. Rank 404

    Chatham Financial

    Regulated
    United States · since 1991· Chatham Financial Corp.
    Wikilix score 88.7
  5. Rank 505

    T.RowePrice

    Regulated
    United States · since 1937· T. Rowe Price Group, Inc
    Wikilix score 87.9
  6. Rank 606

    StoneX

    Regulated
    United States · since 1924· StoneX Group Inc.
    Wikilix score 85.7
  7. Rank 707

    ED&F Man

    Regulated
    United Kingdom · since 2012· ED&F Man Capital Markets
    Wikilix score 85.3
  8. Rank 808

    Ebury

    Regulated
    United Kingdom · since 2009· Ebury Partners Markets Ltd
    Wikilix score 84.8
  9. Rank 909

    ADMIS

    Regulated
    Hong Kong · since 2008· ADMIS Singapore Pte. Limited
    Wikilix score 84.4
  10. Rank 1010

    Fearnley Securities

    Regulated
    Norway · since 1987· Fearnley Securities AS
    Wikilix score 83.8
Ordered by Wikilix score. Each row opens the broker's own record, where every licence is checked against the register.See all 271 on the broker directorySee the individual licences

FCA in the news

5 stories · latest 23 Sept 2026
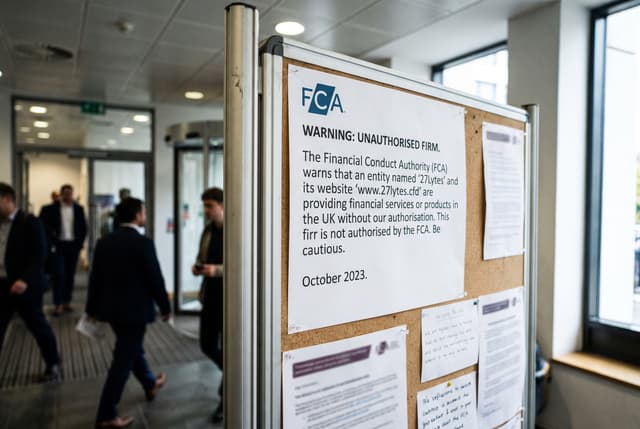
A bulletin board displays an FCA warning notice about an unauthorised firm, with people walking in a modern office setting in the background.FCA Warns 27Lytes May Be Offering Financial Services Without Permission and Targeting UK Consumers23 Sept 2026
  • A man in a suit holding documents stands outside the High Court next to a sign about FCA action against Hunter Jones, with people walking by.FCA takes Hunter Jones operator Osborne Baldwin to High Court over alleged unauthorised loan note sales21 Sept 2026
  • A laptop displaying the FCA website, with a red note saying 'Scam Alert: NovaTask,' papers labeled 'FRN 1016336,' and a coffee cup on a wooden desk.FCA Warns Over NovaTask Clone Using Nova Business Finance Ltd Details to Target Consumers17 Sept 2026
  • A person holds an FCA warning notice next to a laptop displaying the FCA website, with a blurred financial services poster in the background.FCA Warning List Adds www.thinkingmega.com, Says Firm May Be Targeting UK Consumers16 Sept 2026
  • The Upper Tribunal has upheld the FCA's ban on Crispin Odey,Upper Tribunal upholds FCA ban on Crispin Odey and cuts fine to £1.53m14 Sept 2026

About this information

The details on this page about Financial Conduct Authority were compiled from the regulator’s own official documents, its website and other public sources, and are presented as neutral, factual guidance.

If you believe something here is inaccurate, or you spot a critical problem, please let us know via Contact us.