Regulation VerifiedRegulation VerifiedWIKILIX confirmed at least one of its licences on the regulator's official register.
United Kingdom
·Since 1999
Last Updated:
Overall Score75 / 100The Wikilix trust rating of ICAP, out of 100, built from the five factors below.It holds a valid FCA 154234 licence and 6 more, and our investigation found it appears legitimate.Regulation93%Identity98%Client terms51%Trading offer50%Service68%Score last calculated 2026/11/03
Good65 to 79. A solid record with minor gaps and no stop sign.Why: It holds a valid FCA 154234 licence and 6 more, and our investigation found it appears legitimate.
75 out of 100 · 76% checkedThe share of the record we could verify. What we could not check counts as unknown and pulls the score toward the middle, never down.
Do not trust
High risk
Fair
Good
Excellent
It holds a valid FCA 154234 licence and 6 more, and our investigation found it appears legitimate.
We checked ICAP on 2026-11-03 across its regulation, company record, client terms, trading offer and service, and could verify 76% of its record. Its strongest valid licence is FCA 154234, with 6 more valid. The score of 75 is what the checked record adds up to; nothing held it down. What would move the score: licence held by the onboarding entity, pricing disclosed per account type, all-in EURUSD cost. Our published investigation found it appears legitimate, with 31.4 years of track record. Its client terms carry moderate risk, with 6 critical clauses.
Score last calculated 2026/11/03
Regulation
Is someone watching them?
93out of 100
Excellent
Counts for 35% of the score93% checked
What we checked
Best licence in force100
FCA 124520 marked expired by an editor · Oct 14, 2026Source
Whether a financial authority supervises this broker: the licences it holds, whether we verified them on the official register, how strong that regulator is and what protection it gives clients. Worth 35 points of 100.
Identity
Who is behind it, and for how long?
98out of 100
Excellent
Counts for 15% of the score100% checked
What we checked
Registry-verified entity100
Company registration verified on the registry · Oct 14, 2026Source
Verified age100
Verified track record 31.4 years · Oct 14, 2026
Transparency90
Scam check identity transparency 1/10 · Oct 14, 2026
Site integrity100
Website reachable and not redirecting · Oct 14, 2026Source
What this measures
Who is behind it and for how long: a company registration we verified, years of verified history, how openly it names its entity, address and owners, and whether its website is intact. Worth 15 points.
Client terms
Are the client terms fair?
51out of 100
Fair
Counts for 15% of the score100% checked
What we checked
Policy risk45
Policy risk score 5.5/10 · Oct 14, 2026
Critical clauses17
6 critical clause(s) · Oct 14, 2026
Withdrawal rails94
7 rail(s): 7 fee-free of 7 known, 6 instant of 7 known, minimum $50 · Feb 7, 2026
Language parity60
3 contradiction(s) between language versions · Oct 14, 2026
What this measures
How fair the client agreement is: the risk found in our policy review, the number of critical clauses, withdrawal rules, and whether the terms say the same in every language. Worth 15 points.
Trading offer
What does trading cost, and is it disclosed?
50out of 100
Fair
Counts for 20% of the score0% checked
What we checked
All-in EURUSD costNot checked yet
No EURUSD spread known
Pricing disclosed per account typeNot checked yet
No account types recorded
Instrument breadthNot checked yet
No instrument counts known
PlatformsNot checked yet
No trading platform recorded
Leverage vs regulated capNot checked yet
Maximum leverage unknown
Minimum depositNot checked yet
Minimum deposit unknown
What this measures
What trading costs and how clearly it is disclosed: pricing per account type, the all-in cost of EURUSD, instruments, platforms, leverage against regulated limits and the minimum deposit. Worth 20 points.
Service
How do they treat clients?
68out of 100
Good
Counts for 15% of the score90% checked
What we checked
Fund-integrity complaints90
Scam check withdrawal complaints 1/10 · Oct 14, 2026
Support channels50
3 of 6 support checks (phone, email, 24/7 chat, 2+ languages, messenger, complaints email) · Oct 14, 2026
Reputation footprint60
Scam check reputation 4/10 · Oct 14, 2026
WIKILIX communityNot checked yet
0 approved review(s), fewer than 10
What this measures
How clients are treated: support channels, complaints about withdrawals and reputation from our investigation, and reviews by WIKILIX members. Worth 15 points.
What ICAP legally published, but does not want you to read
Wikilix contract reading ·
Moderate contract risk
TP ICAP does not deal with individuals. It says on its own website that any investment offer made to an individual in its name is fraudulent. For the firms it does deal with, the terms are hard. Your cash is not payable while anything is owed anywhere in the group. The platform terms that override the main contract can be rewritten by updating a web page. They cap what TP ICAP owes you at the amount you paid to reach that page.
6Critical clausesClauses that can cost you money you have already earned or deposited, or that remove your ability to challenge it.
27Clauses flaggedEvery clause worth knowing about, at all three severities. Ordinary terms that every broker has are not counted.
65Documents readHow many of the broker’s own legal files this reading is based on. Each one was downloaded and hashed on the date shown.
5.5/10Contract riskHow far this contract goes overall, from 0 to 10. 3 to 5 means real costs a client should know about; 6 to 8 means several clauses put money already earned at risk.
What Wikilix has recorded about ICAP: its history, the licences it holds, its trading conditions and its fees.
ICAP Broker Overview
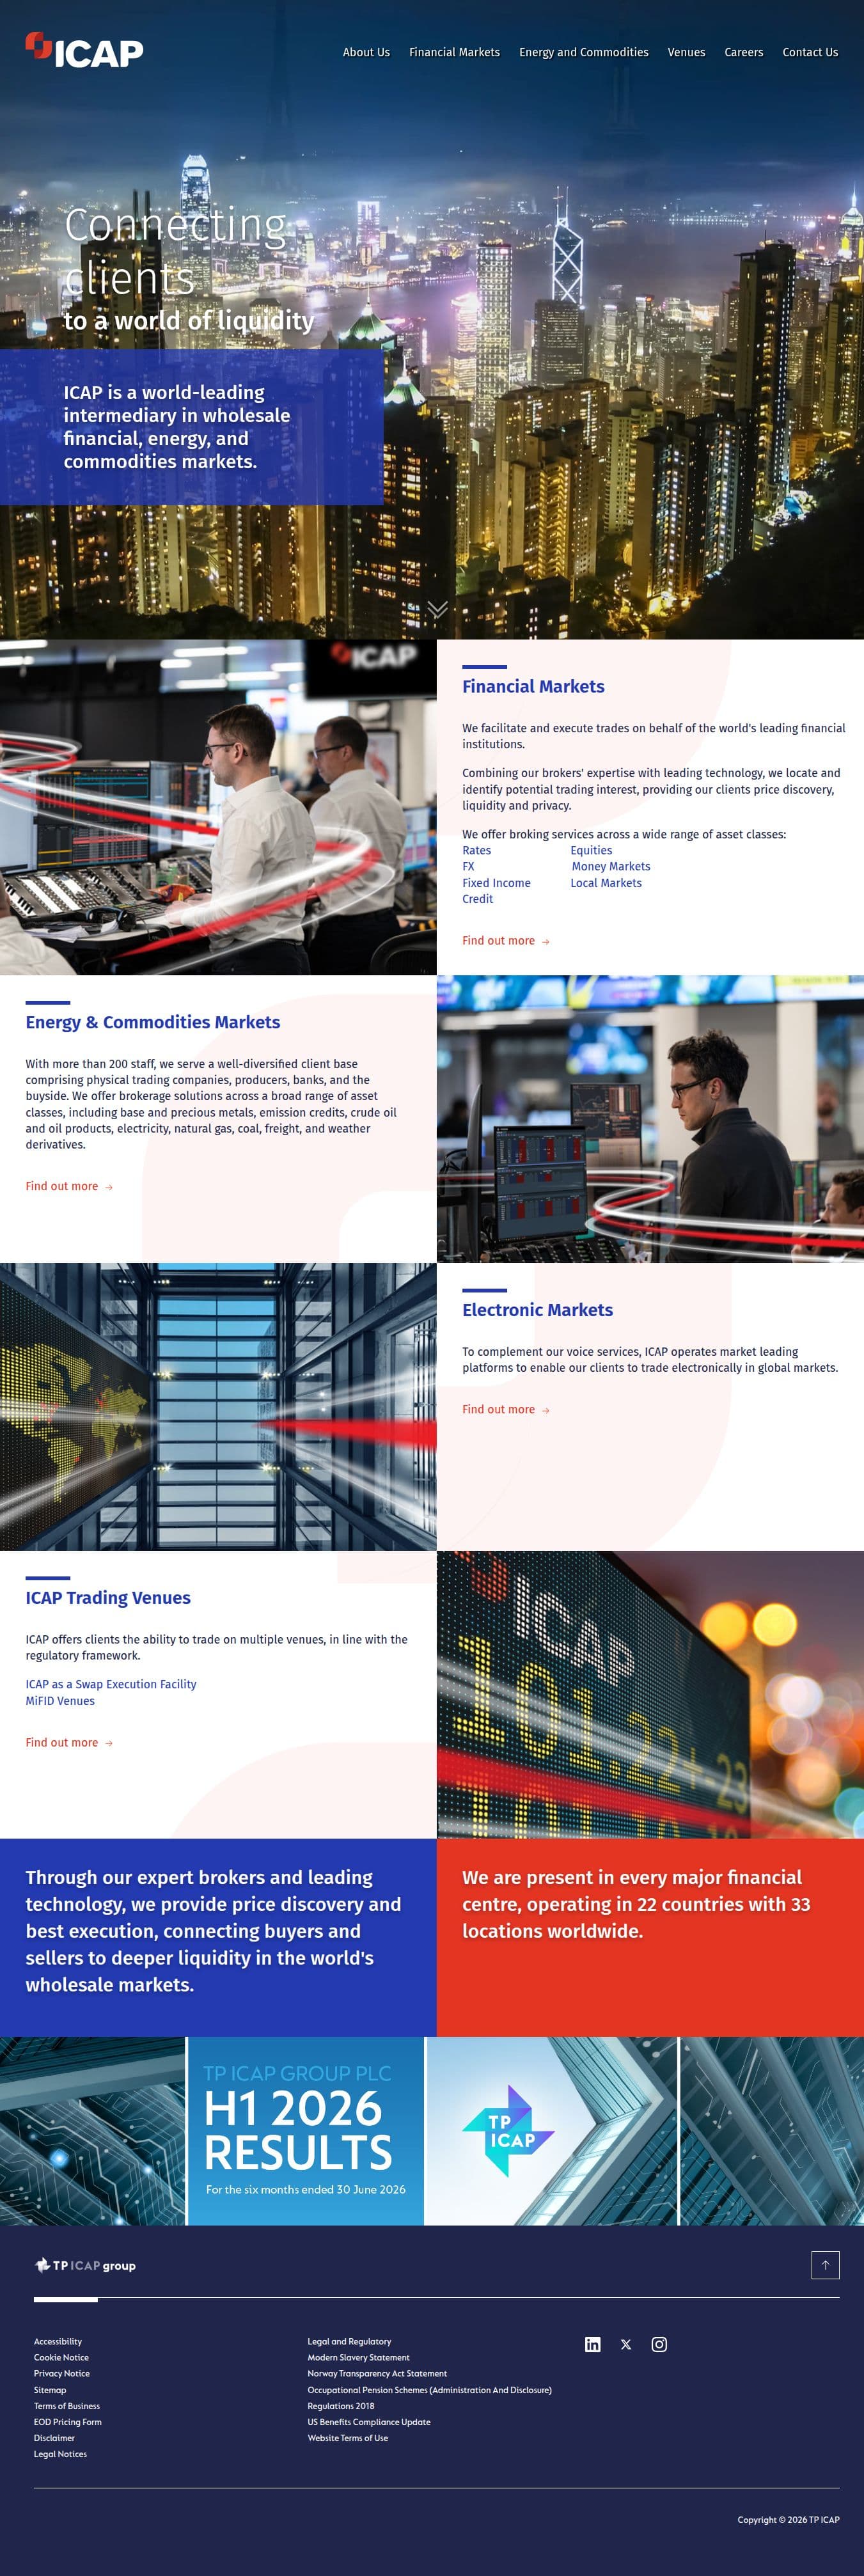
ICAP is the wholesale broking brand of TP ICAP Group plc and has traded under the name since 1999. It is an intermediary between financial institutions rather than a retail forex or CFD broker. Its desks cover Rates, Foreign Exchange and Emerging Markets, Credit, Money Markets and Equities, together with ICAP Relative Value, an Energy and Commodities business and a Global Nuclear Fuels Desk, and business is transacted both by voice and on the group electronic venues. There are no retail trading accounts, no published minimum deposit and no deposit or withdrawal channel on .
ICAP Regulation and License
The Financial Conduct Authority register shows several group companies as Authorised, including TP ICAP Markets Limited (FRN 124520), TP ICAP Broking Limited (FRN 154234) and ICAP Global Derivatives Limited (FRN 191757), all at 135 Bishopsgate, London, with tpicap.com as the recorded website. The group states that it does not offer services to retail investors.
Is ICAP Regulated?
The ICAP broking companies operate inside a United Kingdom regulated group, and several group companies are authorised by the FCA, as its register confirms. That is a different thing from being a regulated retail provider: ICAP publishes no retail client agreement, runs no retail accounts and takes no payments through its site, because it sells to institutions. A reader comparing retail brokers will not find the retail terms, protections or disclosures a retail CFD firm has to publish, for the simple reason that ICAP is not selling that product.
TP ICAP Group plc
ICAP is a brand rather than the legal counterparty. The parent is TP ICAP Group plc, which the group states is registered in Jersey under number 130617. The entities recorded against the business are mainly United Kingdom companies:
TP ICAP Broking Limited, company number 2670499
TP ICAP Markets Limited, 00500777
TP ICAP MTF Limited, 01852009
TP ICAP Commodities Limited, 02533369
TP ICAP E&C Limited, 966604
ICAP Global Derivatives Limited, 03635229
Outside the United Kingdom the record holds TP ICAP (Europe) S.A. in France, TP ICAP Global Markets Americas LLC in the United States and ICAP Energy AS in Norway, registered as 971072032. The group corporate site at carries the legal and regulatory documentation, including separate Terms of Business for the different entities.
Is ICAP Safe?
The question works differently here, because ICAP holds no money for private individuals. The business is long established, the parent publishes annual and half year results and keeps an investor relations contact, and the broking subsidiaries are named with their company numbers, which is more corporate disclosure than most brokers offer. The risk worth naming is impersonation: the ICAP name is well known, so any site offering an ICAP trading account with deposits should be checked against the company itself, since the real business has no client login, no onboarding form and no payment page.
ICAP Account Types
ICAP publishes no account tiers, and no minimum deposit, leverage or commission figure appears anywhere on its site. Access to its electronic platforms is granted to employees of institutional customers that have already been onboarded under the group customer documentation, which covers the onboarding agreements, the relevant venue rulebook or system protocol and a trader authorisation form. The group platform terms set three levels of permission: electronic trading, submitting indications of interest, and view only access to data and prices.
ICAP Spreads, Commissions and Fees
No spread, commission or fee schedule is published. The commercial terms for the ICAP desks sit in the Terms of Business documents the group publishes for its entities on its legal and regulatory hub, which an institutional client agrees before trading, rather than in a public price list.
ICAP Trading Platforms
ICAP runs its own platforms and offers no third party retail software. Fusion is the flagship electronic platform, used across foreign exchange, rates, equities, fixed income, local markets and Asian non deliverable forwards, with volume matching and price discovery tools built in. i-Swap is an electronic venue for interest rate swaps, run as a joint venture between TP ICAP and eight dealer firms. The ICRV platform handles order entry and management for multi leg United States Treasury, futures and options strategies, with real time charting and direct algorithmic access alongside voice, chat, FIX and file based routing. There is no download page anywhere on the site.
ICAP Deposits and Withdrawals
ICAP publishes no deposit or withdrawal methods, and no funding or payment page exists on its site. There is no client wallet, card payment option or e-wallet, because the business does not operate funded retail trading accounts.
ICAP Support
The main contact number on record is +44 (0) 20 7200 7000, and the headquarters address is 135 Bishopsgate, London EC2M 3TP. Client service for the United Kingdom business is reached at ukclientservices@tpicap.com and complaints at complaints@tpicap.com. The group lists offices across the United Kingdom and Europe, the Middle East, Asia Pacific, Australia, New Zealand and the Americas, and support is provided in English. A regulatory hub and a group FAQ sit on the corporate site.
ICAP Pros and Cons
On the positive side: a named parent with a registration number, named broking subsidiaries with company numbers, FCA authorisations confirmed on the register for several group companies, proprietary institutional platforms and a global office footprint.
On the other side, everything follows from who the service is for. There are no retail accounts, no published spreads, commissions or leverage, no deposit or withdrawal channel and no self service onboarding, so an individual cannot compare ICAP with a retail broker on any of the usual terms. The scope of the recorded regulator entries is not set out either, so it should not be assumed.
ICAP Review and Assessment
ICAP is an institutional broking brand of TP ICAP Group plc, and the most important thing to understand before going further is that it is not a retail trading venue. For an institution inside the group onboarding process it offers voice and electronic broking across rates, currencies, credit, equities, energy and commodities. A private trader cannot open or fund an account here, and no pricing is published. Verify any offer of an ICAP retail trading account with the company directly.
Website archive
Captured
Website snapshots
8 full-page captures of ICAP's own site, archived so what they said can still be read after the pages change.
ICAP holds a tier-1 or tier-2 licence that we confirmed on the regulator's own register. Each licence below opens its record of what that register says.
8 of 8 checked
Licences on recordEvery licence or registration recorded for this broker, whether the broker claims it or our check found it.
8
Confirmed on registerLicences we located on the issuing regulator's own public register, with a screenshot taken at the time.
7
Tier 1 or 2Licences from tier-1 or tier-2 authorities (FCA, ASIC, CySEC and peers), the strongest client protection. A registration we could not confirm as a licence is not counted.
7
OffshoreLicences from offshore registers, which typically carry no compensation scheme and lighter oversight.
0
WIKILIX
Licence intelligence
The strongest of 8 licences on file
Licence Verification Record
Financial Conduct Authority154234
Wikilix read the FCA register on Oct 14, 2026. This is what it said.
Jurisdiction
United Kingdom
Authority strength
Tier 1
Register status
Authorised
Effective
Dec 1, 2001
Checked Oct 14, 2026
What our check found
A full UK investment firm authorisation held by TP ICAP Broking Limited, company number 02670499, at 135 Bishopsgate, London. Client protection: Strong supervision of a wholesale broking entity; retail protections do not arise because the firm does not serve private customers. Effective: 01 Dec 2001.
Client protection under this licence
Compensation schemeUp to £85000 (FSCS)
Client money kept separate
Negative balance protection
Complaints routeFinancial Ombudsman Service
Maximum leverage1:30
These are the rules FCA sets for the firms it licenses. They are not a statement about how ICAP applies them, or about which of its companies would hold your account.
A licence record describes what an authority published. It is not an endorsement, and Wikilix does not issue authorisations.
Named as accepted — not a full list of served markets
CACanada
How we know — 12 sources
1ICAP is the wholesale broking brand of TP ICAP Group plc and runs no retail account offering, so the restriction it publishes is by CLIENT CATEGORY rather than by country. Its standing disclaimer at https://tpicap.com/tpicap/disclaimer states the service is "directed to Eligible Counterparties and Professional Customers only and is not intended for Retail Clients (as each term is defined by the rules of the Financial Conduct Authority)", and https://tpicap.com/tpicap/legal-notices adds that the group "does not provide services to private customers".
2The Terms of Business in effect 26 March 2026 (https://tpicap.com/tpicap/sites/g/files/escbpb106/files/regulatorydocuments/2026-03/TP_ICAP_Terms_of_Business%2026%20March%202026_2.PDF) carries no restricted or prohibited jurisdiction clause. Clause 2.6 states the opposite: "The Terms shall apply to you regardless of your jurisdiction to the extent that they are not incompatible with your local legal and regulatory requirements." Clause 5.3 is the only refusal of business in the document: "If you request categorisation as a retail client we will not be able to deal with you."
3The regional TP ICAP (Dubai) Terms of Business of May 2026 (https://tpicap.com/tpicap/sites/g/files/escbpb106/files/2026-05/TP%20ICAP%20DXB%20Terms%20of%20Business%20-%20FINAL%20-%20May%202026.pdf) follows the same pattern: clients are categorised Professional Client or Market Counterparty under DFSA Rules, clause 5.3 repeats the same retail refusal, and no jurisdiction is named. The TP ICAP (Europe) SA, TP ICAP Asia Pacific and ICAP Energy AS terms published on the same legal hub are not covered here.
4No dedicated countries page exists on either of the broker's hosts. The complete icap.com sitemap (https://icap.com/sitemap.xml) is ten pages and holds no such page, and the tpicap.com sitemap lists 359 URLs and holds none either.
5The only FAQ the group publishes (https://tpicap.com/tpicap/regulatory-hub/faq) includes an Onboarding section, yet says nothing about countries, jurisdictions, residence, sanctions or prohibitions. It states that onboarding is arranged by contacting tpicapmifidiionboarding@tpicap.com.
6No signup country list applies because the broker operates no public signup. Onboarding is bilateral and documentary, so no country selector enforces it, and the broker publishes no deposit, withdrawal or introducing-broker pages that might carry their own restrictions.
7The Anti-Money Laundering, Counter Terrorist Financing and Sanctions Policy Statement v3.0 of February 2024 (https://tpicap.com/tpicap/responsibility/our-commitments/anti-money-laundering-counter-terrorist-financing-and-sanctions-policy-statement) commits the group to "fully adhering to international sanctions programs as issued by relevant authorities" and states the firm "will not conduct business, maintain relationships with clients or engage in any transactions or dealings that could result in a violation of applicable Sanctions Laws". It names no sanctions programme and no jurisdiction.
8The Website Terms of Use (https://tpicap.com/tpicap/website-terms-of-use), under "Jurisdictional Issues", reserves discretion instead of naming countries: TP ICAP makes "no representation that ... any Platform, products, instruments or services discussed on the Site are appropriate or available for use or sale in any jurisdiction" and "reserves the right to limit the availability of the Site and/or any Platform thereon to any person, geographic area or jurisdiction it desires, at any time and in its sole discretion". The disclaimer and legal notices add only that the products "may not be eligible for sale in all jurisdictions". Because no jurisdiction is named anywhere, no country or territory is listed as refused or probably refused.
9Canada is the one jurisdiction the broker addresses by name in a client-facing document, which is why it is the only accepted country. The Notice to Canadian Clients - International Dealer Exemption (https://tpicap.com/tpicap/sites/g/files/escbpb106/files/2025-06/Notice%20to%20Canadian%20Clients_updated%2006.2025_TPICAP.pdf) is addressed to "the clients of the following TP ICAP firms located in Canada", namely TP ICAP Markets Limited, TP ICAP E&C Limited, TP ICAP Broking Limited and ICAP Global Derivatives Limited, served under the international dealer exemption in NI 31-103, the CFA international dealer exemption in OSC Rule 32-506 and an Alberta Securities Commission exemption order, with agents for service of process appointed in Ontario, Quebec, Nova Scotia, British Columbia and Alberta.
10No other country counts as accepted. UK authorisation of the operating entities is licence scope rather than a statement about who is onboarded, and Schedule 1 of the Terms of Business gives the Copenhagen branch's contact details rather than saying who that branch accepts, so neither GB nor DK is recorded. This section rests only on documents the broker publishes.
11Iran is neither accepted nor refused. The broker publishes no Persian-language variant: icap.com carries no hreflang tags and no language switcher. No page on either host mentions Iran, Persian-language service or rial funding rails, and the broker runs no funding pages at all.
12Absence of a block is not acceptance. Apart from CA, no country is written to any list, because the broker's own pages neither refuse nor accept any named jurisdiction.
Deposits & withdrawals
Funding Methods
7 ways to fund an account. 7 with no deposit fee. 6 credit instantly.
Bank Wire TransferBank TransferInternational bank wire transfers may take up to 14 days and incur additional intermediary and/or beneficiary fees. Available globally.
This recordUnited Kingdom · since 1999· TP ICAP Group plcWikilix score 75.0RegulationRegulatedFCAMax leverage—Not recordedPlatforms—Not recordedLicences8
ICAP is one of TP ICAP Group plc's broking brands rather than a separate company. Its own site sits at icap.com, while the group corporate site at tpicap.com carries the legal and regulatory documentation, the regulatory hub and the complaints route that apply to the ICAP business.
The headquarters address on record is 135 Bishopsgate, London EC2M 3TP, and the main switchboard is +44 (0) 20 7200 7000. Client service for the United Kingdom business is reached at ukclientservices@tpicap.com and complaints at complaints@tpicap.com.
The group also lists offices across Europe, the Middle East, Asia Pacific, Australia, New Zealand and the Americas.
No. There is no spread, commission or fee schedule on its site. The commercial terms for the ICAP desks are set out in the Terms of Business documents the group publishes for its entities on its legal and regulatory hub rather than in a public price list.
ICAP publishes no leverage, because it does not run retail margin accounts. No leverage cap or account tier appears anywhere on its site.
ICAP is a broking brand of TP ICAP Group plc, which the group states is registered in Jersey under number 130617. The entities recorded behind the business are mainly United Kingdom companies, including TP ICAP Broking Limited (2670499), TP ICAP Markets Limited (00500777), TP ICAP MTF Limited (01852009) and ICAP Global Derivatives Limited (03635229), alongside TP ICAP (Europe) S.A. in France, TP ICAP Global Markets Americas LLC in the United States and ICAP Energy AS in Norway.
No. ICAP publishes no MetaTrader, cTrader or other third party retail platform, and there is no download page anywhere on its site. It runs its own institutional platforms instead.
ICAP offers its own institutional platforms. Fusion is its flagship electronic platform, covering foreign exchange, rates, equities, fixed income, local markets and Asian non deliverable forwards, with volume matching and price discovery tools. i-Swap is an electronic venue for interest rate swaps run as a joint venture between TP ICAP and eight dealer firms, and the ICRV platform handles order entry for multi leg United States Treasury, futures and options strategies.
No. ICAP is a wholesale broker between financial institutions, and its site has no client login, no onboarding form and no payment page. Platform access is granted to employees of institutional customers that have already signed the group customer documentation, which includes the onboarding agreements, the relevant venue rulebook or system protocol and a trader authorisation form.
ICAP brokers wholesale market instruments rather than retail products, organised by desk: Rates, Foreign Exchange and Emerging Markets, Credit, Money Markets and Equities, together with ICAP Relative Value for United States Treasuries, futures and options, an Energy and Commodities business and a Global Nuclear Fuels Desk.
It is an intermediary between financial institutions, so there are no retail forex or CFD accounts, no MetaTrader platforms and no published spreads.
Yes, TP ICAP Group plc offers customer support primarily in English. Support is available via phone, live chat during business hours, and email. The broker also maintains active social media channels including Twitter and LinkedIn for additional contact options.
ICAP publishes no minimum deposit, because it does not operate funded retail trading accounts. Its site has no account tiers, no pricing page and no onboarding form, and platform access is granted to employees of institutions already onboarded under the group customer documentation.
ICAP publishes no deposit or withdrawal methods. There is no funding or payment page on its site, no client wallet and no card or e-wallet option, because the business brokers between institutions rather than holding retail client money.
Anyone asked to deposit money into an ICAP retail trading account should verify who they are dealing with directly with the company.
Yes. The Financial Conduct Authority register shows several group companies as Authorised, including TP ICAP Markets Limited (FRN 124520), TP ICAP Broking Limited (FRN 154234) and ICAP Global Derivatives Limited (FRN 191757). The broking companies behind the ICAP brand are United Kingdom incorporated firms within TP ICAP Group plc, which the group states is registered in Jersey under number 130617.
The group states that it does not offer services to retail investors. Regulation is also not the same as safety, and because ICAP serves institutions rather than individuals, the retail protections a private client would look for are not part of what it offers.
Still Need Help?
Can't find what you're looking for?
Our support team is here to help you get the answers you need.

 United Kingdom




Comments
Share your thoughts and experiences with ICAP